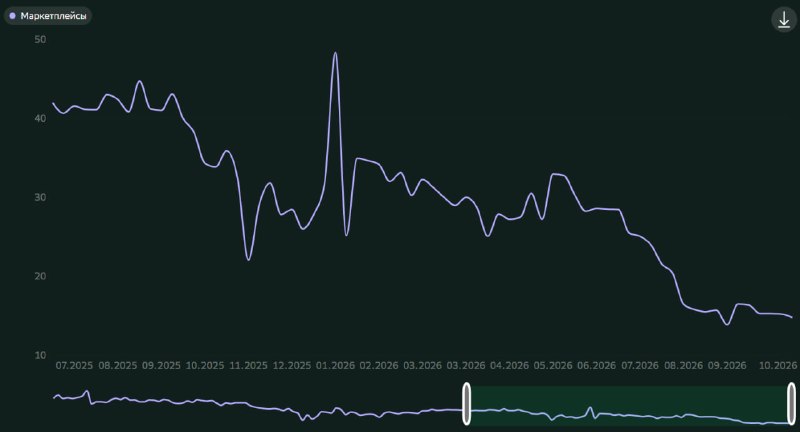
SberIndex data on consumer spending in markets clearly shows that turnover fell in July-August 2026 and has not yet recovered, hovering year-on-year at 15%. However, we now have Ozone's reporting, and it, unlike WB, is publicly traded and severely limited in its ability to hide its financial indicators. In short, Ozone did as expected in the third quarter: revenues grew by 63% year-on-year to 421 billion rubles; The net profit amounted to 3.7 billion rubles; Turnover (GMV) increased by 42% year-on-year and amounted to 1.6 trillion rubles; The losses from UAV attacks amounted to 30 billion rubles. Unlike their main competitor, in the third quarter, i.e. July-September, they did not suffer so much from UAV attacks. Their first warehouse was attacked on August 22, so the market had already taken several steps to minimize the damage, for example, shipping expensive goods to the collection point, and even today, given the renewed attacks on warehouses, they lost much less capacity than WB. Strange people write to me from time to time and claim that they continue to order goods from etc. and everything comes to them, which means that the company is not bankrupt that I was wrong. I really don't understand how they imagine the problems of the company from the point of view of the consumer? For consumers, many times everything will look like business as usual until the last minute. The lack of overall turnover growth for Marketplaces, coupled with a significant increase in turnover for Ozone, again confirms that WB's turnover has declined significantly. Declining turnover, in turn, means declining profits for a company that was already consistently unprofitable. No partner warehouses would compensate them for losing large warehouses, which allowed them to lower logistics costs. But WB can't raise the percentage for sellers; The only thing that still keeps them there is more favorable working conditions than in ozone.
SberIndex data on consumer spending in markets clearly shows that turnover fell in July-August 2026 and has not yet recovered, hovering year-on-year at 15%. However, we now have Ozone's reporting, and it, unlike WB, is publicly traded and severely limited in its ability to hide its financial indicators. In short, Ozone did as expected in the third quarter: revenues grew by 63% year-on-year to 421 billion rubles; The net profit amounted to 3.7 billion rubles; Turnover (GMV) increased by 42% year-on-year and amounted to 1.6 trillion rubles; The losses from UAV attacks amounted to 30 billion rubles. Unlike their main competitor, in the third quarter, i.e. July-September, they did not suffer so much from UAV attacks. Their first warehouse was attacked on August 22, so the market had already taken several steps to minimize the damage, for example, shipping expensive goods to the collection point, and even today, given the renewed attacks on warehouses, they lost much less capacity than WB. Strange people write to me from time to time and claim that they continue to order goods from etc. and everything comes to them, which means that the company is not bankrupt that I was wrong. I really don't understand how they imagine the problems of the company from the point of view of the consumer? For consumers, many times everything will look like business as usual until the last minute. The lack of overall turnover growth for Marketplaces, coupled with a significant increase in turnover for Ozone, again confirms that WB's turnover has declined significantly. Declining turnover, in turn, means declining profits for a company that was already consistently unprofitable. No partner warehouses would compensate them for losing large warehouses, which allowed them to lower logistics costs. But WB can't raise the percentage for sellers; The only thing that still keeps them there is more favorable working conditions than in ozone.
More on Radar
Want to see every report in real time?
Hundreds of sources worldwide, translated into your language, with alerts for what matters to you.
Sign up free Already have an account? Log in