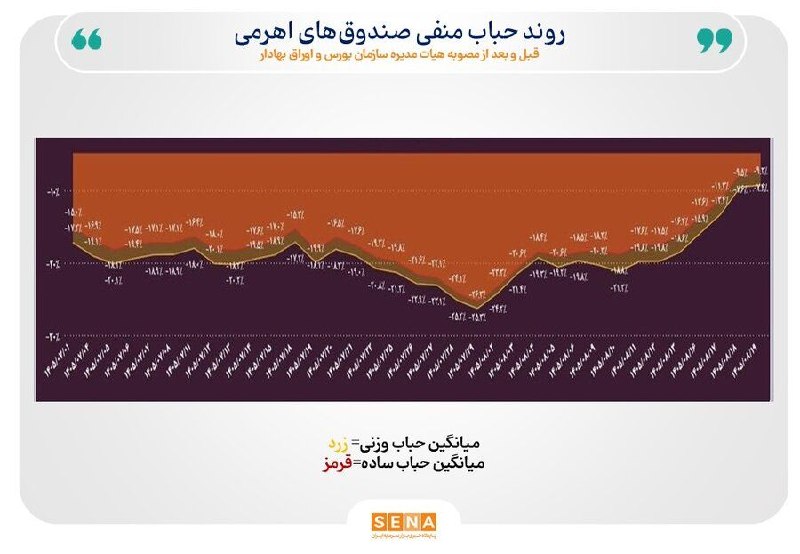
Projecting the first results of the correction package of the Board of Directors of the Securities Exchange Organization.
The card is back to leveraged trading.
The negative bubble of leveraged funds dropped from 25% to less than 8%.
Recent data from the Subsidiary for the Supervision of Financial Institutions of the Securities Organization shows that following the implementation of the reform package of the Board of Directors of the Stock Exchange Organization, the weighted average of the negative bubble of the leveraged funds decreased by 17.7 percentage points, from minus 25.3 percent to minus 7.6 percent. These results were revealed while all the components of the reform package of the board of directors of the stock exchange organization have not yet been implemented. The package of amendments of the Board of Directors of the Exchange Organization was approved and announced on October 22 of this year.
A review of the trading process in leveraged funds shows that the process of reducing the distance between the trading prices of these units and their net asset value (NAV) began on the first trading day after the publication of the reform package by the stock exchange organization, so that a significant part of this gap was reduced in less than 3 weeks.
According to the statistics of the Center for Monitoring Investment Funds, the weighted average of the negative bubble of the leveraged funds that reached minus 25.3% in the last days of Mahar 1,405, dropped to minus 7.6% at the end of trading on November 10. This change is equivalent to an improvement of about 17.7% in a gap of 70% to the initial price to NAV. The simple average of the negative bubble of the leveraged funds also reached a negative 9.3% on the same date.
Changing the route from the first day after the confirmation message.
A review of the trading data shows that from the first day of trading after the announcement of the Board of Directors of the Stock Exchange organization, that is on the second Saturday of November, the process of strengthening the negative bubble of the leveraged funds stopped and the movement of trading prices towards the net asset value began.
This trend has gained more momentum since Saturday, November 7, after the daily volatility range of leveraged fund tradable units increased from positive and negative 4% to positive and negative 6%.
The mentioned changes indicate a significant simultaneity of the announcement and the beginning of the implementation of the reform package with the improvement of the situation of leveraged fund transactions; However, the exact assessment of the contribution of each of the reforms in these changes requires further investigations and separation between the effects of other market factors.
A look at the four pack of the Board of Directors of the Stock Exchange Organization.