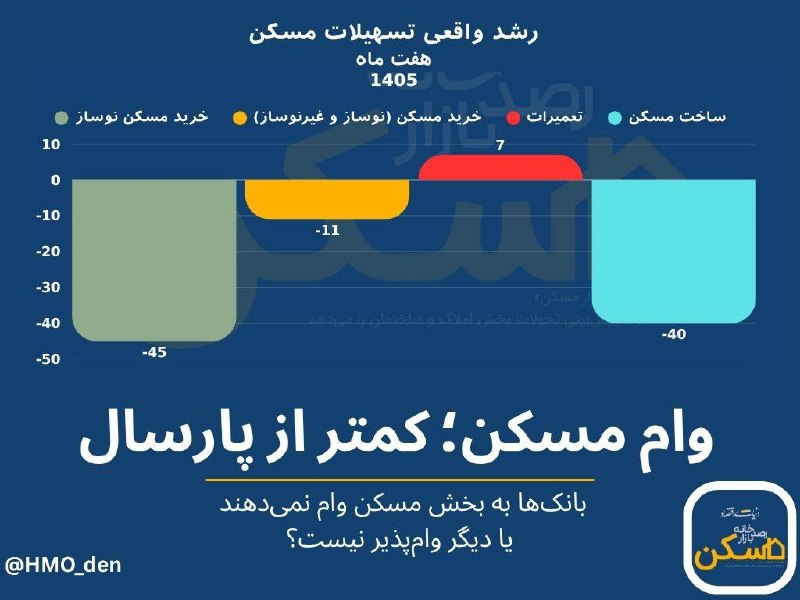
Banking thermometer for housing purchase; The banks don't give mortgages or the market doesn't take it? Housing market outlook: 1 Housing market loan conditions have become worse than last year. 2 In the first 7 months of the year, only 3.2% of the total payment frameworks of the banking network.
It was awarded to builders, home buyers and home repair applicants. 3 This share was 4% last year, which of course did not fit "at all" into the housing financing system. 4 The housing and construction sector attracted about 20% of banking facilities in the 1980s.
And in the 90's its share was still double digits. 5 Now, however, the financial burden of the housing market has "declined". 6. A home loan plays the role of a "stick" for home buyers.
In various countries, at least 60 to 70 percent and on average 80 percent of the "housing purchase budget" is financed by bank loans. 7 Builders can afford two-thirds of the cost they spend on housing production on bank facilities. 8 Even governments to support projects such as rental housing or renovation of dilapidated buildings, one of their main tools is "banking facilities". (Read the role of housing loans in the regeneration of Istanbul here) 9 In Iran's housing market, there is a great shortage of facilities. In the last months of this year, the real value of the purchase loan paid for the purchase of a newly built home decreased by 45%.
מנקודת מבט זו, הקיפאון ברכישת מבנים חדשים כבד יותר משאר יחידות המגורים. 1 1 גם הצמיחה הריאלית של הלוואות בנייה הפכה לשלילית של 40%. סקרים של מצפה שוק הדיור לגבי הסיבה לצמיחה שלילית זו בהלוואות מראים: מהצד של מבקשי הלוואות רכישה, 3 סיבות הן כוח הקנייה הנמוך של משקי הבית, אותה תקרה להלוואות רכישה שנבנו לאחרונה ולא משופצות והמחסור היחסי ביחידות חדשות שנבנו בשוק המכירות גרמו לירידת הערך הריאלי של ההלוואות. בשוק הדיור בטהרן, סכום של מיליארד הלוואות רכישה מכסה רק חמש עשרה ממחיר דירה חדשה שנבנתה; כיסוי לא יעיל לחלוטין. בצד מבקשי הלוואות בניה, בשל "מיתון הבנייה עקב אי מכירת יחידות במיתון המסחר" וגם "חלק של 25% מההלוואה בכיסוי עלות הבנייה".
There is no willingness on the part of the builders to accept loans. But the reasons for the stagnation of loans to the housing sector also have a third party.